
Download the Visual
In radioligand therapy, manufacturing is the first gate, not the last
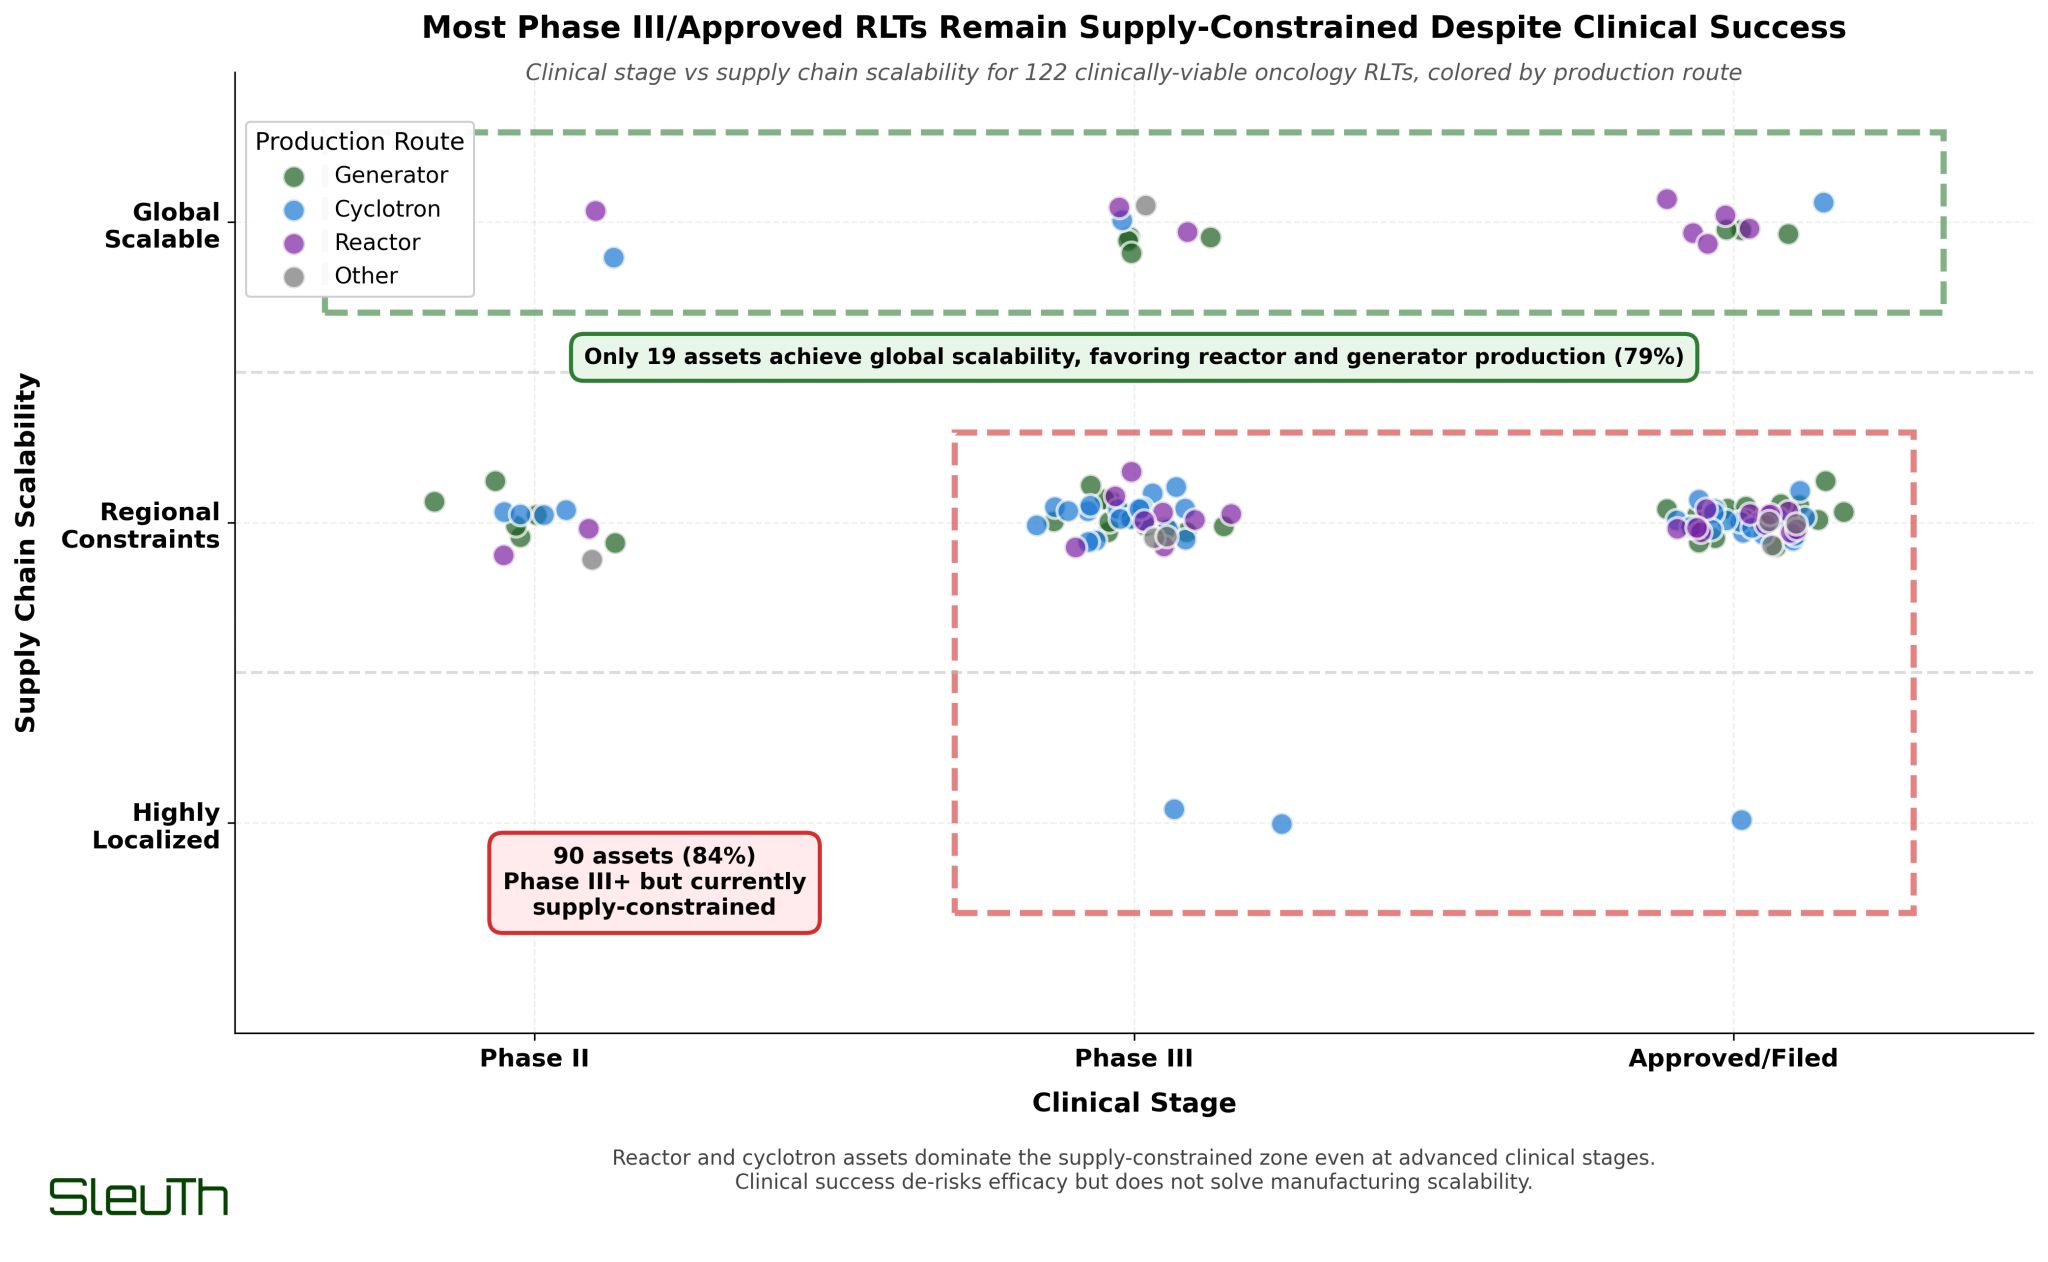
Most late-stage oncology radioligand therapies (RLTs) remain supply-constrained despite clinical success. In Sleuth’s January 2026 analysis of 122 clinically viable oncology RLTs, 90 assets in Phase 3, filed or approved, 84% of that late-stage group, were rated supply-constrained. BD teams that filter for Phase 3 data, pivotal trials and durable responses, and treat manufacturing as secondary diligence, have the order backwards.
Manufacturing scalability separates global products from regional ones more decisively than clinical differentiation does, because in RLT the supply chain is part of the product.
Only 19 of 122 clinically viable RLTs reach global scale
Just 19 of the 122 assets are rated globally scalable, and 79% of those use reactor or generator production. All but three of the rest are rated regionally constrained; the three are cyclotron-produced assets, two in Phase 3 and one approved or filed, rated highly localized. Reactor and cyclotron assets dominate the supply-constrained group even at the most advanced clinical stages.
This analysis’s approved-or-filed group is broader than the list of approved radioligand therapies. Sleuth’s Q3 2026 radiopharma report counts only therapeutic RLTs and found two approved, Novartis’s Lutathera and Pluvicto, as of August 2026, so the two pages measure different things.
Clinical success de-risks efficacy but does not solve manufacturing scalability.
Production route sets each asset’s market ceiling
Cyclotron distribution is bounded by decay physics: many cyclotron isotopes have half-lives measured in hours, which rules out profitable cross-continent shipping. Reactor capacity is concentrated in aging facilities prone to shutdowns, and building lutetium-177 supply at Pluvicto’s scale took years of dedicated partnerships. Novartis built dedicated supply infrastructure for Pluvicto and Lutathera, both reactor-produced, while most newer reactor programs assume a supply chain that does not yet exist for them.
Generator-produced radionuclides such as Ga-68, Tc-99m and Y-90 ease distribution because they can be eluted and radiolabeled on site in a hospital radiopharmacy, collapsing global logistics into local chemistry. The generators still depend on reactor or accelerator production of their parent isotopes, and in Sleuth’s ratings generator assets appear among both the globally scalable and the regionally constrained.
The moat in RLT is removed distribution risk, not better science, and on-site labeling reduces that risk without guaranteeing scale.
What the supply constraint means for RLT investors
These implications are Sleuth’s interpretation of the data.
- Run manufacturing diligence before clinical diligence. If an asset depends on reactor or cyclotron supply without solved distribution, its addressable market is regional regardless of efficacy.
- Discount Phase 3 valuations for unresolved manufacturing. Clinical success proves efficacy, not commercial potential.
- Treat manufacturing constraints as white space. Indications where RLT competition is sparse, such as I&I, neurology and rare disease, are often sparse because manufacturing has not been solved there yet.
Sleuth’s Q3 2026 radiopharma report, from August 2026, extends the argument: for approved RLTs the tightest constraint has moved downstream from lutetium-177 supply to treatment chairs, staff and reimbursement, and actinium-225 supply is the next bottleneck for alpha emitters. The same gate appears in China biotech partnering, where manufacturing readiness decides which late-stage assets can reach a US or EU deal.
How Sleuth built this analysis
Which RLTs count as clinically viable
The 122 assets are oncology RLTs in Phase 2 or later with trial maturity that supports registrational potential.
How supply scalability was rated
Sleuth rated each asset’s supply chain, based on its production route, as globally scalable, regionally constrained or highly localized. Supply-constrained means rated regionally constrained or highly localized.
Asset counts and supply ratings come from Sleuth’s analysis published in January 2026, and this page is a dated snapshot.
Frequently asked questions about RLT manufacturing and supply
How many late-stage radioligand therapies are supply-constrained?
In Sleuth’s January 2026 analysis of 122 clinically viable oncology RLTs, 90 assets in Phase 3, filed or approved, 84% of that group, were rated supply-constrained. Only 19 of the 122 were rated globally scalable.
Which RLT production routes scale best?
Reactor and generator production account for 79% of the 19 globally scalable assets in Sleuth’s January 2026 analysis, while reactor and cyclotron assets dominate the supply-constrained group. Generator isotopes can be labeled on site in hospital radiopharmacies.
Why do cyclotron-produced RLTs struggle to scale?
Many cyclotron isotopes have half-lives measured in hours, so doses cannot be shipped profitably across continents. In Sleuth’s January 2026 analysis, the only assets rated highly localized were three cyclotron-produced RLTs.